Area Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

July 20, 2022

As the market for homes in Houston cools a bit, sellers are lowering the prices


As fewer buyers come into the market, home sellers in Houston are cutting their asking prices. This is another sign that the housing market is cooling.


Recent information from two major real estate agencies shows that more people in Houston are lowering the prices they want for their homes. Redfin, a residential brokerage, says that prices were cut on more than a third (38%) of the homes for sale in the Houston area in June. Redfin says that about 25% of homes in Houston had price drops a year ago.


On the other hand, Zillow's numbers are more conservative. They say that 16.8% of Houston homes for sale had their prices cut in June, which is up about 5.6 percentage points from the same month last year.


Even though the numbers are different, they show that home sellers may be starting to lose the advantage they had during the pandemic.


"Home sellers are dealing with a market that is changing quickly," said Redfin Senior Economist Sheharyar Bokhari in a statement. "This is especially true in areas where they're used to seeing their neighbors' homes get multiple offers and sell for more than the asking price." "Potential buyers in popular places to move are putting their plans on hold because mortgage rates are going up and there could be a recession. Sellers are changing their expectations as they realize they might not get the same price as their neighbor did two months ago.


A small town north of Houston is getting a 400-acre luxury home development.


Houston home sellers, on the other hand, don't seem to be under as much pressure to lower their prices as sellers in other major metros, where a rush of people moving because of the pandemic may have led to bigger real estate gains earlier in the pandemic.


According to Redfin, Boise was one of the most popular places for people to move because of a pandemic. As a result, the average home price there jumped to $550,000 in May, which was more than a 60% increase from two years earlier. Based on Redfin's analysis, 61.5 percent of homes for sale in Boise had their prices cut in June, which was the most of any city in the country.


According to the Redfin analysis, more than 25% of sellers in about three quarters of the country's biggest cities lowered their asking prices.


In Texas, home sellers are seeing the biggest price drops in Austin, where a lot of people moved because of the pandemic and drove up real estate prices quickly. Redfin says that the prices of about 41.6% of the homes for sale in Austin dropped in June, compared to only 14.9% at the same time last year. In June, the prices of about 37.5% of the homes for sale in Dallas and San Antonio dropped, which was a little less than in Houston.


Even though the market isn't as crazy as it used to be, prices are still going up, albeit at a slower rate. Most metro areas in Texas are still getting a lot of out-of-state buyers because homes are still relatively affordable. In California, for example, a typical home sells for more than $1.5 million in many of the state's biggest cities.


The Houston Association of Realtors says that the average price of a home in Houston in June was $436,000. On Redfin's list of the top cities where people wanted to move, San Antonio was ninth, Dallas was tenth, and Houston was eleventh.


Redfin's Deputy Chief Economist Taylor Marr said, "These factors, along with the fact that more companies are giving employees the permanent option to work from home, are making more buyers think about homes in other parts of the country." "Someone who couldn't buy a home in Los Angeles without going over their budget might be able to in Phoenix or San Antonio."


Marr could have also said something about Houston. In the second quarter, the top places where Redfin users who didn't already live in Houston were looking to move from were Los Angeles, New York City, and the Bay Area.


Houston Gay Realtor Real Estate Agent
Leslie Don Wilson
Realtor - ABR AHWD ALHS CIPS CNE CRS GREEN GRI MCNE SFR SRES TRLP
Houston - 281-804-2291 
DFW - 214-702-3447 
Texas Pride Realty Group
Brokered by: HomeSmart Stars 


July 19, 2022

New Report Ranks Houston Highly For Industrial Building

In the Houston area, more than 145 Costco stores' worth of industrial space is being built. This makes Houston the No. 2 market in the Southwest for warehouses and distribution centers that are still being built.


The Community Property Executive put out information that showed about 21.2 million square feet of industrial space was being built in Greater Houston. According to the report, this number is equal to 3.9% of the total stock, which has grown to 547.8 million square feet. In other words, all of that space is the same as more than 145 Costcos.


In particular, almost 4.9 million square feet of industrial space became available in the first half of 2022. Even though the survey says it's hard to predict how much will be finished by the end of the year, the volumes of the previous years have been similar and may end up being higher than this year's: 19.6 million square feet of industrial space, or 3.8 percent of the total stock, was delivered in 2021, and 19.7 million square feet, or 3.9 percent of the total stock, was added in 2020.


The report mentions two important industrial changes in the area. Article, an online furniture store based in Canada, and TGS Cedar Port Industrial Park in Baytown share a 507,000-square-foot warehouse. At more than 15,000 acres, Cedar Port is the largest industrial park in the U.S. that is planned and served by rail and barge.


In other parts of Texas, Dallas-Fort Worth is at the top of the list and the country, with almost 60,6 million square feet of industrial space being built as of late June. That's a little more than 7 percent of the more than 840 million square feet of industrial space already in the area. Based on the numbers, that's about the same as 324 average Walmart supercenters.


Austin, with 8.3 million people, El Paso, with more than 5.7 million people, and San Antonio are also big cities (almost 4 million).


In a recent REPORT, commercial real estate services company Cushman & Wakefield says, "The COVID-19 pandemic brought new challenges to the industrial market, such as port congestion, material shortages, and skyrocketing commodity prices. However, the market has and will continue to do well."

View More
July 18, 2022

Where You’ll Move if You Sell Your House

If you placed a halt on your home hunt because you weren't sure where you'd go, it may be time to return. Because the market is shifting, there are more homes for sale. That means you may locate a property that meets your needs. Some options:

Existing homes provide lived-in charm.

According to the National Association of Realtors (NAR), the existing house supply has risen since the beginning of the year. The graph below shows increased inventory due to more properties entering the market and slower sales.

If you want a home with lived-in appeal, supply is rising, which is good news.

Danielle Hale, Chief Economist at realtor.com, explains why more homeowners are listing their houses today.

“Home sellers in many markets profit from rising prices and speedy sales. This year, more homeowners are selling than previous, offering buyers more options. This year, more properties are for sale than previous.

Existing homes provide several perks. Older homes have a unique charm that's hard to replicate. Existing homes are frequently in established neighborhoods with mature landscaping that boosts seclusion and aesthetic appeal.

Timing also matters. With an existing home, you can move in when you and the sellers agree, unlike with a new home. Remember this if you need to move soon.

While more sellers are listing, supply remains low. You'll have more alternatives when searching for your future house, but be prepared for a quick market.

Buying a new home means everything is new.

Census data shows more new homes for sale. It comprises under-construction, near-completion, and finished homes. As the graph below shows, there are more new homes for sale this year.

When creating a new home, you can tailor it to your lifestyle. That could include energy-efficient solutions or design aspects. New appliances, windows, roofing, etc. These can cut your energy expenditures, which can mount up over time.

Newer homes are also lower-maintenance. When you have a new home, you won't have as many small repairs, like leaking faucets, to do. With new construction, warranty options may protect your investment for the first several years.


Buying a new house may require a long wait before moving in. Robert Dietz, NAHB's Chief Economist and Senior Vice President for Economics and Housing Policy, explains:


New single-family homes have a 7.7-month supply. Only 8.3% of new homes are ready to move in. 25.9% haven't started construction or are in progress.

You should discuss this with a trusted real estate advisor before making a decision. They'll weigh the advantages and downsides of new and existing homes to help you decide.


Overall

With more homes for sale, you have options no matter your preferences. If you have questions or need help deciding, let's talk.

Posted in Buyer, Seller
July 15, 2022

Should I Rent or Should I Buy?

Some Key Points

Before you decide whether to rent or buy a home, you should think about all the good things that come with owning one.

When you buy a home, you can keep your housing costs stable, own something tangible, and increase your net worth as you build equity. When you rent, your housing costs will go up, you won't get a return on your money, and you won't be able to save as much.

Let's talk today if you want to find out more about the benefits of owning your own home.


Posted in Buyer, Landlords, Seller
July 14, 2022

This Isn’t a Bubble (According To Housing Experts)

Some people are wondering, with all the talk about an economic slowdown, if the housing market is going to crash like it did in 2008. To really understand what's going on in real estate right now, it's important to get information from experts you can trust.


Here are some of the reasons why economists and industry experts say the housing market is not a bubble that is about to burst.


2008 is not like today.


Many people who bought or sold a home in 2008 still remember the housing crash. But the market of today is different. Odeta Kushi, First American's Deputy Chief Economist, says:


"This market is not the same as it was in 2008. It's no secret that the housing market was a major cause of the Great Recession, but this market is so different in so many ways that it can't be compared.


Forbes Advisor Staff Member Natalie Campisi explains how today's lending standards are different from those before the housing market crash:


"One difference between the housing market now and before the 2008 crash is that lending standards are tighter. This is because people learned from the last crisis and new rules were put in place. Basically, this means that people who get a mortgage today are less likely to stop paying than those who got one before the financial crisis.


The number of people looking to buy a home is still higher than the number of homes that are for sale. This is another way that the housing market today is different from the market in 2008. As realtor.com notes:


"Experts don't think the market is in a bubble or that a crash like the Great Recession is coming. The country still has a housing shortage that has reached a crisis level at a time when many millennials are getting old enough to start thinking about buying a home. Prices are likely to stay high as a result."


Bottom Line


Experts say that the housing market is not in a bubble and that we are not about to have a crash. Let's talk so you can get a full picture of what's going on in the housing market in our area right now.


Amelia and I on vacation in Gavelston

Houston Real Estate BOSS - Leslie Don Wilson Houston RE BOSS
Leslie Don Wilson
Realtor - ABR AHWD ALHS CIPS CNE CRS GREEN GRI MCNE SFR SRES TRLP
Houston - 281-804-2291 
DFW - 214-702-3447 
Texas Pride Realty Group
Brokered by: HomeSmart Stars 
June 27, 2022

Why Pre-Approval Is an Important Step for Today’s Homebuyers

This time of year, if you want to buy a house, you have to be smart and competitive. Today, pre-approval is so important because of this. The only way to know your true price range and how much money you can borrow for your loan is to get pre-approval from a lender. Editor of The Mortgage Reports Peter Warden tells us:


"The lender will look into your finances and send you a letter letting you know how much you can borrow. This not only gives you a clear idea of how much you can spend on a house, but also lets sellers know you're ready to make an offer."


Why is that so important now? Today, there are many more people looking for homes than there are homes for sale, which means there is a lot of competition. The National Association of Realtors (NAR) says that the average home gets 4.8 offers when it goes on the market and sells. So, there are still a lot of bidding wars.


In these situations, your pre-approval gives you an advantage. That's because you know exactly how much you can borrow before you write your offer, and it lets the seller know you're qualified to buy their home. This makes both you and the seller feel good about what you have to offer. And that makes it more likely that you could win a bidding war.


As Warden puts it:

"Getting preapproved is also important for another reason. This is because there are way more buyers than homes on the market right now. If you want to win a bidding war, you need to be very ready. Right now, most sellers are getting more than one offer. And most won't even look at an offer if it doesn't come with a preapproval letter."


In a market that is always changing, every advantage you can get as a buyer is important. The interest rates on mortgages are going up, home prices are going up, and lending institutions are always changing their requirements. You'll need help to find your way through these waters, so it's important to have a loan officer and a trusted real estate advisor on your side. They'll help you get ready to show off your best side.


Bottom Line

Getting pre-approved for a mortgage helps you figure out what you can afford and shows sellers that you're serious about buying their home. Let's talk so you can get the tools you need to buy a home in the current market.


Houston Gay Real Estate Agent Realtor Leslie Don Wilson


--

Leslie Don Wilson
Realtor - ABR AHWD ALHS CIPS CNE CRS GREEN GRI MCNE SFR SRES TRLP
Houston - 281-804-2291 
DFW - 214-702-3447 
Texas Pride Realty Group
Brokered by: HomeSmart Stars 
Posted in Buyer, Landlords
June 24, 2022

Why an Agent Is Essential When Pricing Your House

Some Highlights

  • When it comes to pricing your house, there’s a lot to consider. The only way to ensure you price it right is by partnering with a local real estate professional.
  • To find the best price, your agent balances current market demand, the values of homes in your neighborhood, where prices are headed, and your home’s condition.
  • Don’t pick just any price for your house. If you’re ready to sell, let’s connect to find the perfect price for your house.

Houston Gay Realtor Real Estate Agent Leslie Don Wilson Houston Real Estate BOSS

Houston Gay Real Estate Agent Realtor Real Estate BOSS Leslie Don Wilson

Houston Gay Real Estate Agent Realtor Real Estate BOSS Leslie Don Wilson

Posted in Investors, Seller
June 23, 2022

Hedge Against the Impact of Rising Inflation

If you've been paying attention to the news lately, you know that inflation is going up. Inflation is at its highest level in 40 years. The National Association of Home Builders (NAHB) says the following:


"Consumer prices went up again in May, as prices for housing, energy, and food kept going up at the fastest rate in decades. This was the first time since December 1981 that the rate of inflation was higher than 8% for three months in a row.


As prices go up for gas, groceries, and other things, you may be able to tell that inflation is going up. The rising cost of goods and services can put a strain on your budget and make you think twice about any big purchases you were planning.


If you've been thinking about buying a home this year, you might be wondering if you should go ahead or if it would be better to wait. The answer depends on your situation, but here are some ways that being a homeowner can help you deal with the rising costs caused by inflation.


Buying a home helps you keep one of your biggest monthly costs stable.


Investopedia says that when there is a lot of inflation, prices go up everywhere. This is true for food, entertainment, and many other goods and services, including housing. Prices for both homes and apartments are going up. So, how can you, as a buyer, protect yourself from rising prices? The answer is to buy a house.


When you buy a home, you can stabilize what is usually your biggest monthly cost: housing. With a fixed-rate mortgage, your monthly payment stays the same for the life of the loan, which is usually between 15 and 30 years. Senior Wealth Management Reporter at Bankrate, James Royal, says:


"A fixed-rate mortgage lets you keep most of your housing costs at the same payment amount. Even though your property taxes will go up and you may have to pay more for other things, your monthly housing payment will stay the same. If you rent, that's certainly not the case."


So, even if the prices of other things go up, your rent will stay the same, which will help you keep your budget in order. If you rent, you don't have that benefit, and you won't be protected from rising housing costs.


Putting money into something that has historically done better than inflation


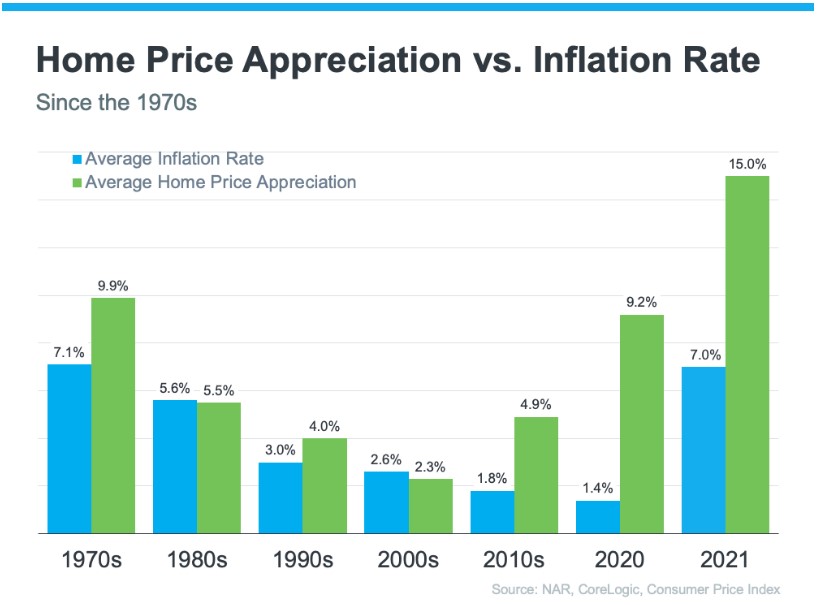
While it’s true rising home prices and higher mortgage rates mean that buying a house today costs more than it did even a few months ago, you still have an opportunity to set yourself up for a long-term win. When inflation is high, you want your money to be invested in something that does better than inflation and usually holds or grows in value.


The graph below shows how the average home price appreciation outperformed the average inflation rate in most decades going all the way back to the seventies – making homeownership a historically strong hedge against inflation (see graph below):

So, how does that affect you? Experts think that home prices will only go up from here on out because supply and demand are still not in balance. If the price of your home goes up after you buy it, your equity and your net worth will grow. And because homes are usually assets that increase in value over time, you can be sure that your investment is a good one.

That means that if you are ready and able, you should buy now before prices go up even more.


Bottom Line

Even though prices are going up, if you want to buy a house this year, it makes sense to do it soon. So, you can keep your monthly housing costs stable and put your money into an asset that has historically done better than inflation. If you're ready to get started, let's talk so that when you're ready to buy a home, you can get expert advice on your specific situation.


Houston Gay Realtor Real Estate Agent

Houston Gay REal Estate Agent Realtor

Posted in Buyer, Landlords, Seller
June 22, 2022

Don't Do These Things After You Apply For A Mortgage

After you have applied for a mortgage to buy a home, there are a few important things to remember. Even though it's fun to think about moving in and decorating, don't make any big purchases just yet. Here are a few things you probably didn't know you shouldn't do after getting a home loan.


Don't put in a lot of cash.


Lenders need to know where your money came from, and cash is hard to track down. Before you put any cash into your account, talk to your loan officer about the right way to keep track of your transactions.


Don't buy anything too big.


You could lose your loan if you buy something that isn't related to your home. Lenders may be worried about any big purchases. When a person has new debt, their debt-to-income ratio goes up (how much debt you have compared to your monthly income). Since loans with higher ratios are riskier, the borrower may no longer be able to get a mortgage. Don't give in to the urge to buy anything big, even furniture or appliances.


Don't sign loans for other people.


When you co-sign for a loan, you agree to be responsible for making sure the loan is paid back. With this obligation, the ratio of debt to income will also go up. Even if you say you won't make the payments, your lender will still count them against you.


Don't move your money around.


Lenders must be able to find and keep track of your assets. This job is much easier to do when all of your accounts are the same. Talk to your loan officer before you send any money.


Don't try to get more credit.


It doesn't matter if you're getting a new car or a new credit card. Your FICO® score will be affected when your credit report is checked by multiple companies (mortgage, credit card, auto loan, etc.). Your mortgage interest rate and maybe even your ability to get a mortgage can be affected by how low your credit score is.


Don't get rid of any accounts.


Many buyers think that having less credit makes them less of a risk and makes it more likely that they will be approved. This is wrong. A big part of your credit score is how long and how well you've used credit (not just how well you've paid bills) and how much of your available credit you've used. Both of these parts of your score will go down if you close accounts.


In short, talk to a professional.


In short, be honest with your lender about any changes when you talk to them. Changes in your income, assets, or credit score should be looked at and handled in a way that makes sure you can still get a home loan. Tell your lender if your job or employment status has changed since you last talked to them. In the end, it's best to tell your loan officer everything you plan to do before you do anything related to money.


Bottom Line


You want everything to go as smoothly as possible when you buy a house. Remember that you should talk to your lender before you make any big purchases, move your money around, or make any big changes in your life. Your lender is the best person to explain how your financial decisions may affect your home loan.

Houston Gay Realtor Real Estate Agent

Houston Real Estate BOSS - Leslie Don WilsonHouston Gay Real Estate Agent Realtor

Posted in Buyer
June 21, 2022

The Average Homeowner Gained $64K in Equity over the Past Year

If you own a home, your net worth probably just went up a lot because your home equity is going up. Equity is how much your home is worth now minus how much you still owe on the loan. And because home prices have been going up recently, you're building equity much faster than you might think. Here's how it works.


Home prices are going up because there aren't enough homes for sale to meet the demand for them. That means that your home is in high demand and is worth more on the market right now. As CoreLogic's President and CEO, Patrick Dodd, says:


"Price growth is the most important factor in building home equity wealth.... This has led to the largest one-year gain in average home equity wealth for owners...."


Your equity has probably gone up because the value of your home has probably gone up so much. CoreLogic's latest Homeowner Equity Insights report says that over the past year, the average homeowner's equity has grown by $64,000.


Even though that is the number for the whole country, you can use the map below to find out what's going on in your area. Using data from CoreLogic, it shows how much equity has grown on average from one year to the next in each state.

The Chance Your Increasing Home Equity Gives You

Equity can help you reach other goals, like buying your next home, as well as help you build your overall net worth. When you sell your current home, you get back the equity you've built up. In a market where homeowners are gaining so much equity, it may be just what you need to cover most or all of the down payment on your next home.


So, if you've been waiting to sell or are worried that you won't be able to afford your next home because of how much home prices are going up right now, you can rest assured that your equity can help you move.


Bottom Line

If you want to move, the equity you've built up in your home can make a big difference. Let's talk so you can get a professional report on your home's equity. This will tell you how much equity you have and how you can use it to pay for your next purchase.

Houston Real Estate BOSS - Houston Gay Realtor Real Estate Agent

Houston Real Estate BOSS - Houston Gay Realtor Real Estate Agent

Houston Real Estate BOSS - Houston Gay Realtor Real Estate Agent